Key findings (DealMachine mortgage data, October 2026)
- Of the 4.76 million first mortgages recorded in 2026, 86% carry a rate between 6% and 7%. Only 0.9% are under 4%.
- Among first mortgages recorded since 2010, loans at 7% or more are 2.1 times as likely to be absentee-owned as loans under 4% (36.8% vs. 17.7%).
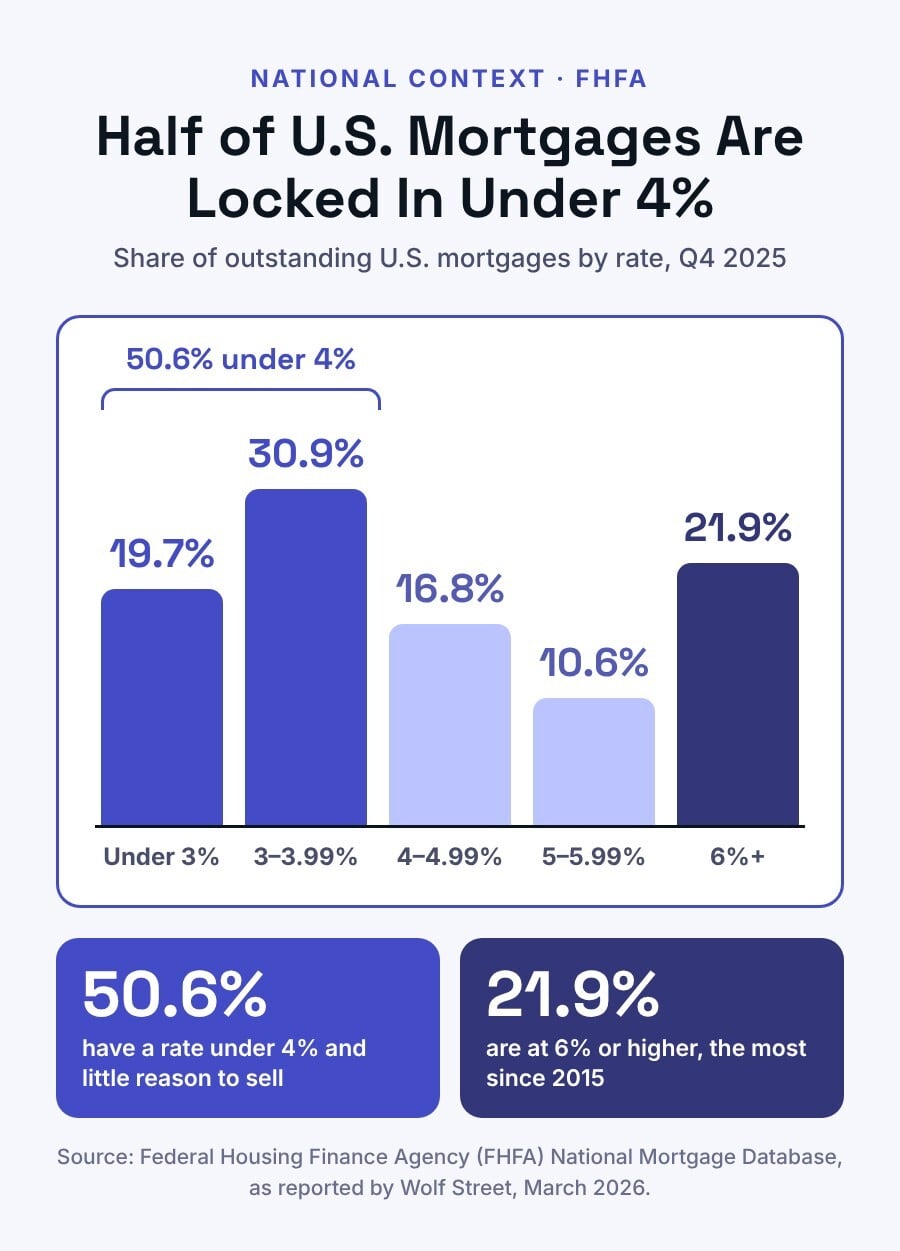
Housing inventory is low because about half of U.S. homeowners have a mortgage rate they don't want to give up. According to the Federal Housing Finance Agency (FHFA), 50.6% of U.S. mortgages had a rate under 4% at the end of 2025. Selling means trading it for a loan at today's rates, so they stay put.
That's the lock-in. Our data shows it's starting to break, and which owners feel the most pressure.
Why Housing Inventory Is Frozen
Here's how I think about it. A $300,000 loan at 3% costs about $1,265 a month in principal and interest. The same loan at 6.5% costs about $1,896. That's roughly $630 more every month for the same amount of debt.
Most people won't take that deal unless a job move, a divorce, or a growing family forces it. Fewer sellers means fewer listings, and fewer listings means low inventory.
The FHFA data also shows the other side. As Wolf Street reported from FHFA figures, 21.9% of mortgages carried a rate of 6% or higher in Q4 2025, the highest share since 2015.